
It’s 3:00 PM on a Tuesday, the Central Florida humidity is climbing toward 100 percent, and your air conditioner has finally given up. Seeing the replacement costs for 2026 equipment can cause instant sticker shock, especially with new SEER2 regulations and the transition to A2L refrigerants driving prices higher. You need a cool home immediately, but you also need a payment plan that doesn’t drain your savings. Finding reliable ac financing florida options is the best way to bridge the gap between an emergency breakdown and a comfortable home.
We understand that a new HVAC system is a major investment. Since 2006, we’ve helped homeowners manage these technical transitions with confidence and clarity. You’re likely feeling overwhelmed by the choice between PACE programs, traditional bank loans, and manufacturer rebates. This guide clarifies the process so you can secure a high-efficiency system with manageable monthly payments. We’ll examine the reality of 0% APR offers, explain why the federal 25C tax credit is no longer an option in 2026, and show you how to find utility rebates that lower your total cost. You will gain a clear plan to restore your comfort without the financial stress.
Key Takeaways
- Understand the various ac financing florida pathways that allow you to manage the costs of new SEER2 compliant systems without a large upfront payment.
- Compare the benefits of the Florida PACE program against traditional manufacturer credit to find the most stable solution for your specific household budget.
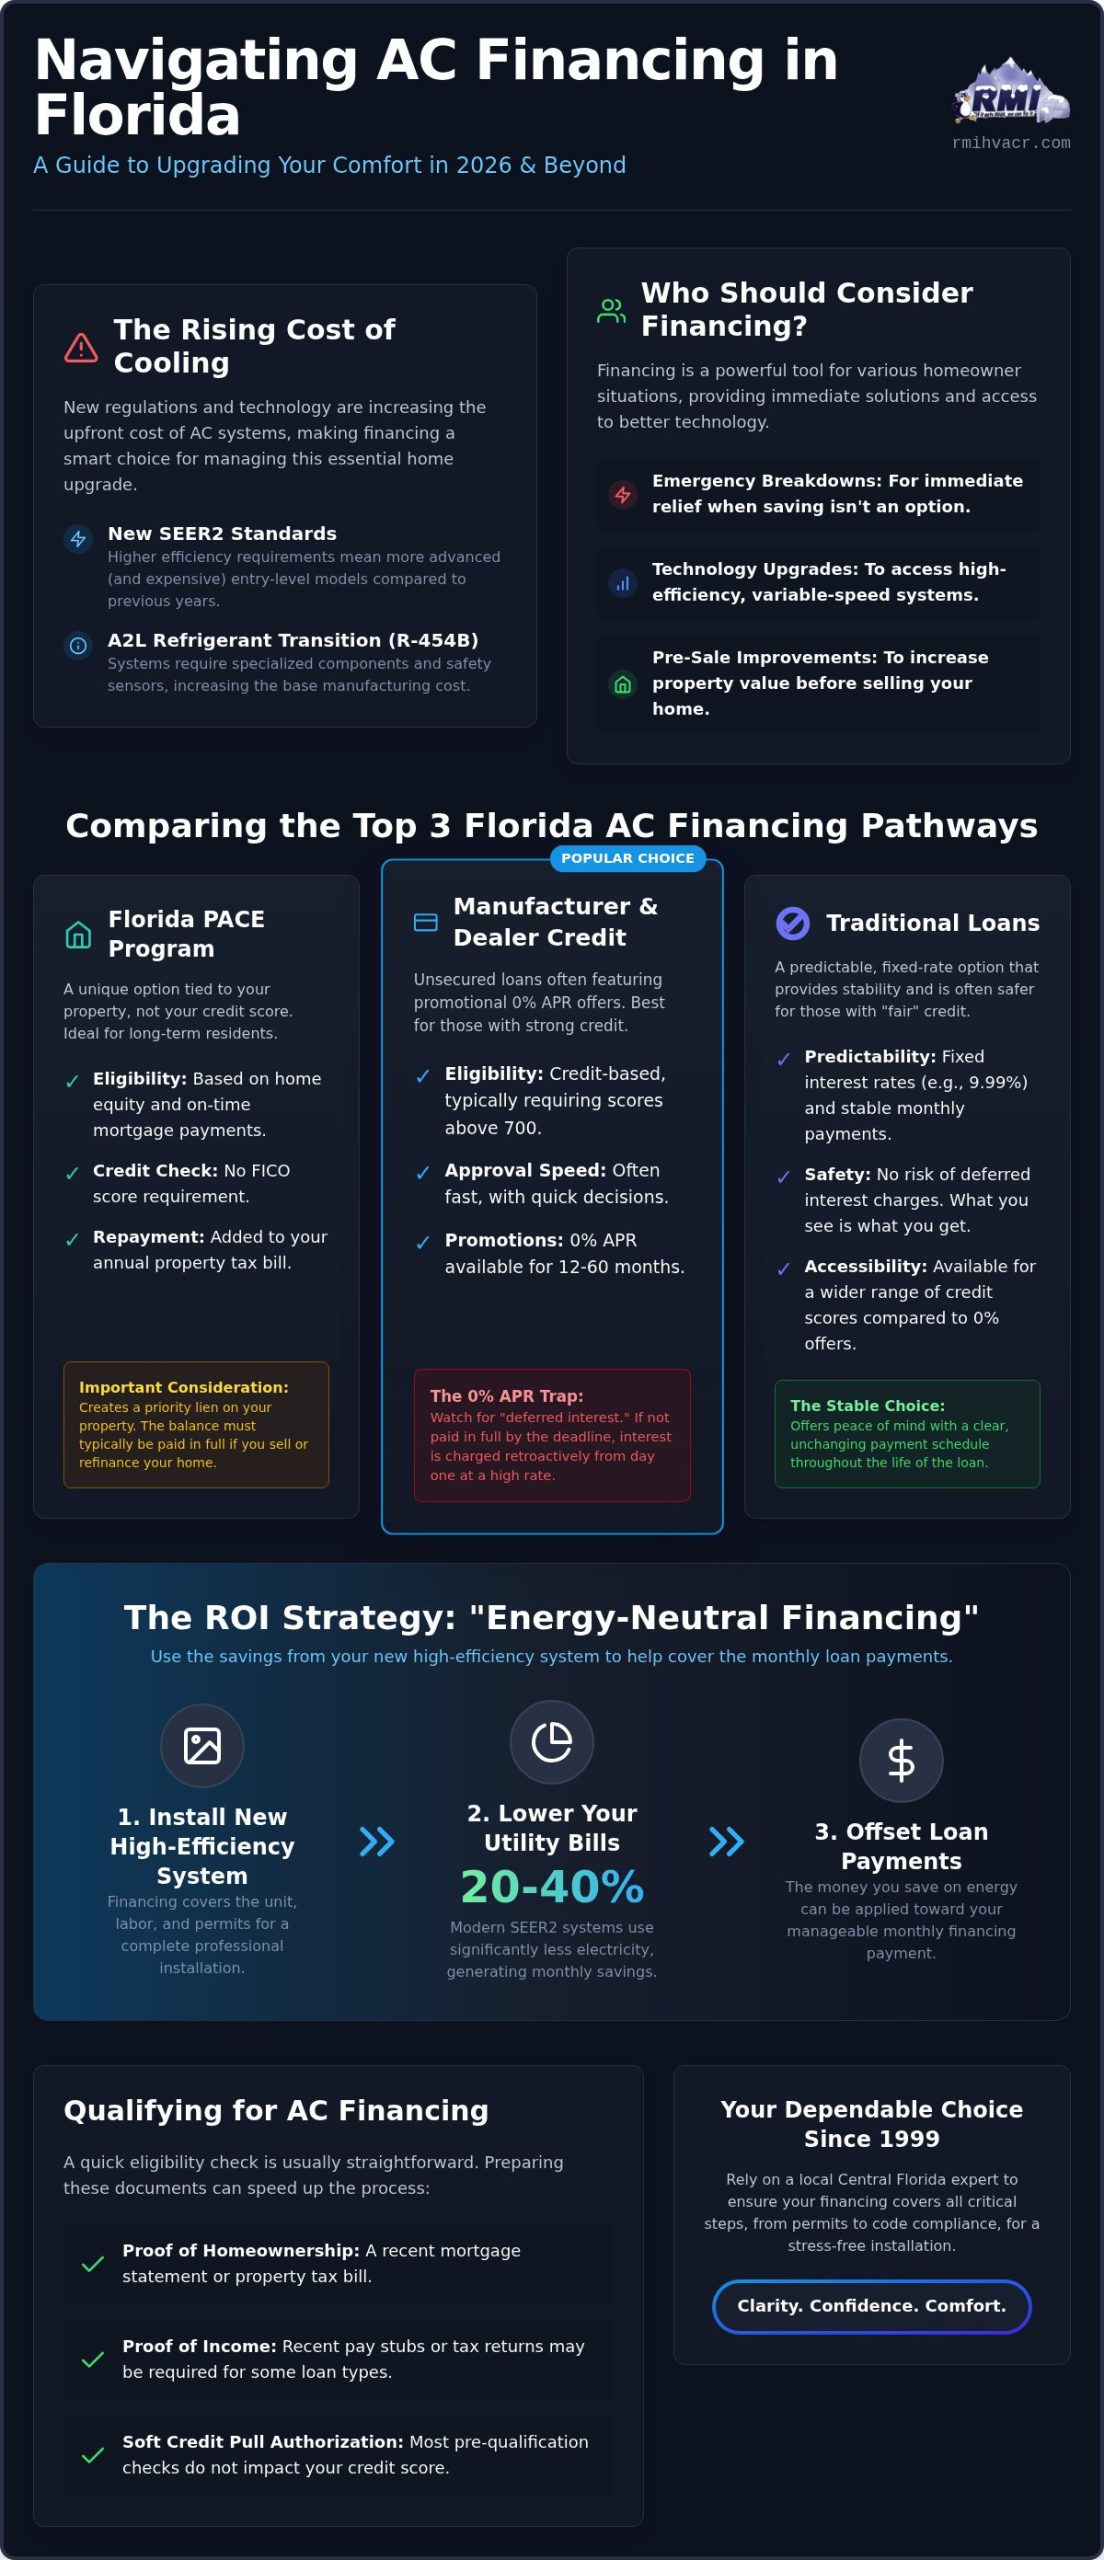
- Learn how “energy-neutral financing” uses the 20 to 40 percent savings on your monthly utility bills to help pay for a high-efficiency HVAC upgrade.
- Identify the essential documents needed for a quick eligibility check, including proof of homeownership and income, often available through a simple soft credit pull.
- Rely on a local expert with a history in Central Florida since 2006 to ensure your financing covers critical steps like permits and code compliance.
Understanding AC Financing Options in Florida for 2026
Managing the heat in Central Florida is a necessity, not a luxury. In 2026, the price of staying cool has shifted due to new federal standards and manufacturing changes. Using ac financing florida options provides a dependable pathway to handle these expenses without depleting your emergency savings. This financial tool covers the entire scope of the project. It includes the high-efficiency unit, expert labor, required mechanical permits, and even ductwork repairs. Since 2006, we’ve seen how professional financing turns a stressful breakdown into a manageable home upgrade.
You generally choose between two loan structures. Unsecured options are credit-based and don’t require your home as collateral. They offer fast approval times for those with solid credit histories. Secured options, such as PACE programs, are tied to the property itself. These are often accessible to a wider range of homeowners because they prioritize home equity over credit scores. Both paths allow you to secure a reliable cooling system while keeping your monthly cash flow stable.
The Rising Cost of Cooling: Why Financing is Essential
The industry transition to A2L refrigerants, specifically R-454B, has increased the base cost of equipment. These new systems require specialized components and safety sensors to operate legally and safely. Additionally, 2026 SEER2 requirements mean even entry-level models are more advanced and expensive than units from five years ago. Large-scale home improvement projects like an HVAC overhaul are now significant investments. While the upfront sticker price is higher, the total cost of ownership is often lower because these systems use significantly less electricity.
Who Should Consider Financing Their AC Unit?
Emergency situations are the most common reason for seeking ac financing florida services. If your system fails during a July heatwave, waiting months to save for a cash purchase isn’t a safe option. Financing allows for immediate relief and professional installation. It’s also ideal for those wanting to upgrade to variable-speed technology. These systems offer superior humidity control, which is vital in Ocala and The Villages. Finally, if you’re preparing for an air conditioning replacement before selling your home, a new, financed system can increase your property’s value. We prioritize preparedness by helping you find a solution that fits your budget without cutting corners on quality.
Comparing the Top 3 Florida AC Financing Pathways
Selecting the right funding method is just as important as choosing the right SEER2 unit. If you are researching which brands offer the best efficiency for your home, you can visit Air Conditioner Lab for independent reviews and comparisons. Since 2006, we’ve helped Central Florida residents identify which ac financing florida pathway aligns with their long-term goals. Every household has different priorities, whether it’s preserving cash flow, bypassing credit checks, or maximizing tax benefits. We focus on transparency so you can avoid hidden fees and high-interest traps. A stable financial plan is the foundation of a dependable cooling system.
The Property Assessed Clean Energy (PACE) program is a unique option for Florida homeowners who may not qualify for traditional bank loans. Instead of a monthly check to a lender, you repay the cost through a non-ad valorem assessment on your annual property tax bill. Eligibility depends on your home equity and a history of on-time mortgage payments rather than a FICO score. This makes it highly accessible. However, it’s vital to understand that PACE creates a priority lien on your property. If you plan to sell or refinance your home in Ocala or The Villages soon, most mortgage lenders will require the PACE balance to be paid in full at closing. It’s a powerful tool for long-term residents, but it requires careful exit planning.
Manufacturer and Dealer Financing: The 0% APR Trap
Manufacturer-sponsored credit programs, often managed through providers like Wells Fargo or Synchrony, frequently advertise 0% APR for 12 to 60 months. These offers are excellent for homeowners with credit scores typically above 700. The danger lies in the “deferred interest” clause. If the balance isn’t paid in full by the end of the promotional period, interest is often charged retroactively from the original purchase date at a much higher rate. For those with “fair” credit, a standard interest-bearing loan with a fixed rate near 9.99% is often a safer, more predictable choice. These plans offer consistent monthly payments without the risk of a massive interest spike if your circumstances change. You should also check the Florida Energy Saver Program for updates on rebates that can be paired with these loans to reduce your total financed amount.
Personal home improvement loans and Home Equity Lines of Credit (HELOCs) serve as a third alternative. Personal loans provide fast funding without using your home as collateral, while HELOCs offer lower interest rates for those willing to wait through a longer approval process. If you aren’t sure which path fits your budget, our team can help you review your options during an air conditioning installation consultation to ensure you’re fully prepared for the investment.
The ROI Strategy: Using Financing to Lower Monthly Bills
Many homeowners view a new HVAC system as a pure expense. In Florida, a strategic approach to ac financing florida turns this investment into a tool for monthly savings. We focus on “energy-neutral financing,” a concept where the reduction in your utility bill offsets a large portion of your loan payment. A high-efficiency SEER2 unit can reduce monthly power consumption by 20 to 40 percent compared to an aging 10-year-old system. When you spread the cost of the equipment over several years, the math often reveals that the system pays for itself through lower overhead.
Florida’s cooling season lasts nearly ten months. This extended runtime makes the efficiency of your compressor the most significant factor in your long-term budget. Variable-speed technology allows the unit to adjust its output based on the actual cooling demand rather than running at full blast constantly. This precision saves electricity and reduces wear on the components. By choosing a financed premium system, you secure these savings immediately rather than waiting years to save up for a cash purchase while paying inflated energy bills.
High-Efficiency Systems vs. Standard Units
Buying a base-model unit with cash might seem like the thrifty choice, but it often leads to higher long-term costs. A standard unit struggles to manage Central Florida’s intense humidity, forcing it to run longer cycles. Premium units excel at moisture removal. This humidity control serves as a hidden financial benefit by preventing mold growth and protecting your home’s structure. You can explore high-efficiency models on our air conditioning replacement page to see how these advanced systems compare. Financing a premium unit allows you to enjoy superior comfort and lower bills for a predictable monthly fee.
Utility Rebates and 2026 Incentives
The financial landscape for HVAC upgrades has changed recently. While the federal 25C tax credit under the Inflation Reduction Act expired for installations after December 31, 2025, other incentives remain active. Florida utility companies like Duke Energy and FPL continue to offer instant rebates for qualifying high-efficiency systems. These rebates can often be applied directly to your project cost, reducing the total amount you need to finance. It’s essential to select a system that meets specific SEER2 thresholds to qualify for these programs. We prioritize preparedness by helping you identify which units maximize your immediate rebates and long-term energy savings. Using these incentives to pay down your loan principal early can further reduce your interest costs over the life of the financing agreement.
Qualifying for AC Financing in Central Florida
Applying for ac financing florida programs is a straightforward process designed to get your home cool as quickly as possible. Most lenders require three basic pieces of documentation: a valid government-issued ID, proof of steady income, and verification of homeownership. Since 2006, we’ve seen how a prepared homeowner can move from application to approval in as little as 15 minutes. Many modern HVAC lenders now utilize “soft credit pulls.” This allows you to check your eligibility and see potential interest rates without any negative impact on your credit score.
The timeline for project funding is efficient. Once you choose a plan and sign the digital documents, the funds are typically secured within 24 to 48 hours. For homeowners with lower credit scores who may not qualify for prime bank rates, secondary options like lease-to-own programs provide a vital safety net. These programs focus more on your history of utility payments and home equity rather than just a FICO score. This ensures that every resident in Orlando or The Villages has a pathway to a functional, high-efficiency system during a crisis.
Stacking Local Utility Rebates in Orlando and Ocala
Maximizing your investment involves “stacking” different financial incentives. Central Florida utility providers like Duke Energy and OUC (Orlando Utilities Commission) offer specific rebates for upgrading to high-efficiency equipment. For instance, Duke Energy provides rebates for systems that meet certain SEER2 benchmarks. Our technicians handle the technical documentation and AHRI certificates required for these approvals. To maximize your savings, you should follow this checklist:
- Verify your system meets the 15.2 SEER2 minimum required for most utility rebates.
- Ensure your contractor is a registered participant in the specific utility’s program.
- Apply for financing that allows you to pay down the principal once your rebate check arrives.
By combining these local rebates with structured financing, you significantly lower the net cost of your new unit. This approach ensures you aren’t just paying for a box, but investing in a long-term efficiency plan.
The Role of the Contractor in the Financing Process
A lender will not approve a loan without a professional AC installation quote based on accurate data. We provide a comprehensive Manual J load calculation to ensure the system size matches your home’s specific needs. This prevents the common mistake of financing a unit that is too large or too small, which leads to premature failure and high energy bills. Be wary of “financing-first” companies that prioritize loan approval over technical accuracy. These outfits often skip permits and code compliance to hide the cost of high dealer fees. We prioritize a stable, professional approach that ensures your financing covers a system installed to the highest standards. If you’re ready to see which options fit your budget, you can request a professional quote today to begin the qualification process.
Why RMI Heating and Air Conditioning is the Dependable Choice for Florida Financing
RMI Heating and Air Conditioning has remained a stable presence in Central Florida since 2006. We recognize that choosing ac financing florida is about more than just numbers; it’s a long term commitment to your household’s safety and comfort. Our team operates with a core philosophy of preparedness. This means we help you find a financial path that fits your monthly budget without ever cutting corners on the technical side of the job. We don’t ignore vital details like mechanical permits or code compliance. Every system we install meets strict Florida building codes and hurricane rated mounting requirements. This attention to detail protects your property and ensures your lender is financing a legally compliant, high standard asset.
Whether you need assistance with a single family residential unit or have complex commercial HVAC financing needs, our experience ensures a smooth, professional process. We act as a dependable guide through the technical paperwork and lender requirements. Stability is a critical factor when you enter a multi year payment plan. You need a contractor who has been here for decades and will remain here for the entire life of your loan. We prioritize getting the job done right the first time so you can focus on your life, not your thermostat.
Our Commitment to Transparent Pricing
Lenders and homeowners alike trust us because we provide clear, honest estimates. Our quotes are comprehensive. They include every necessary component, from the high efficiency unit itself to expert labor and necessary permits. This transparency prevents the hidden fee surprises that can often derail a financing application at the last minute. Our technicians arrive in fully stocked trucks, ready to handle the installation with precision. This readiness respects your time and protects your investment from the moment we arrive on site. Once your new system is up and running, we recommend enrolling in our AC maintenance plans. This protects your financed system, ensures it stays within warranty, and keeps it running at peak efficiency for years to come.
Get Your Professional Estimate Today
The Florida heat is relentless. Waiting until the humidity peaks to replace a failing unit can lead to dangerous indoor temperatures and rushed financial decisions. We offer expert consultations throughout Orlando, Ocala, and The Villages. Our team provides a precise Manual J calculation to ensure your new system is sized perfectly for your specific square footage. We simplify the path to a cooler, more efficient home with reliable ac financing florida options. Apply for AC financing and schedule your installation with RMI Heating and Air Conditioning today.
Secure Your Home Comfort with Dependable Financing
The transition to 2026 SEER2 standards and new refrigerant requirements doesn’t have to be a source of financial stress. By utilizing the right ac financing florida options, you can upgrade to a high-efficiency system that lowers your monthly utility bills while providing superior humidity control. Whether you choose a PACE program for its accessibility or a traditional manufacturer loan for its competitive rates, the goal remains the same: a cool home without the upfront sticker shock. High-efficiency technology is now more accessible than ever through structured payment plans that protect your cash flow.
Since 2006, RMI Heating and Air Conditioning has been the stable choice for homeowners in Orlando, Ocala, and The Villages. We provide expert guidance on every loan type and ensure your A+ rated professional installation meets all local building codes and hurricane requirements. Our team prioritizes your preparedness, ensuring you have a reliable system that stands up to the relentless Florida heat. Don’t let an aging unit compromise your comfort or your budget. Explore AC Financing Options with RMI today and take the first step toward a more efficient home. We’re ready to help you find the perfect balance of performance and affordability.
Frequently Asked Questions
Does AC financing in Florida require a high credit score?
No, a high credit score is not always mandatory to qualify for ac financing florida. While prime lenders typically look for a FICO score of 700 or higher to offer the lowest interest rates, many secondary lenders provide options for those with “fair” or “poor” credit. Additionally, programs like PACE prioritize your home equity and mortgage payment history over traditional credit scores. This ensures that most homeowners can find a path to a reliable cooling system.
How does the Florida PACE program work for AC replacement?
The Florida PACE program allows you to finance energy-efficient upgrades without a traditional credit check. Instead of making monthly payments to a bank, the cost is added as a non-ad valorem assessment to your annual property tax bill. Eligibility is primarily based on the equity in your home and your history of on-time mortgage payments. It provides a stable way for residents to afford high-efficiency SEER2 units that meet current 2026 regulations.
Can I finance a new AC unit if I am a renter in Florida?
Generally, renters cannot finance a new AC unit because the equipment becomes a permanent fixture of the property. Financing agreements typically require the applicant to be the legal owner of the home. If your system fails, you should contact your landlord immediately. They are responsible for providing a functional HVAC system under Florida law. Landlords can often use ac financing florida options themselves to manage the cost of a replacement for their rental property.
What is the typical monthly payment for a financed AC system in 2026?
Monthly payments vary based on the total project cost, interest rate, and the length of the loan term. Most homeowners see payments ranging from $125 to $250 per month for a standard high-efficiency system. Choosing a longer term, such as 60 or 84 months, can lower your monthly obligation. We recommend reviewing different loan structures during your consultation to find a payment that aligns with your household budget and long-term financial goals.
Are there 0% interest AC financing options available in Orlando?
Yes, many manufacturer-sponsored programs offer 0% interest promotional periods in the Orlando area. These plans often range from 12 to 60 months. It is vital to understand if the offer is “true 0%” or “deferred interest.” In deferred plans, if the balance isn’t paid in full by the end of the promotion, interest is charged retroactively from the installation date. Always read the fine print to ensure the terms match your repayment plan.
Will financing an AC unit include the cost of new ductwork?
Yes, most HVAC financing plans allow you to include the cost of new ductwork, air quality services, and professional installation. Since even the most efficient SEER2 unit cannot perform correctly with leaky or undersized ducts, bundling these costs is a smart strategy. Including ductwork in your initial financing ensures your entire system operates at peak efficiency from day one. This comprehensive approach protects your investment and maximizes your monthly energy savings in the long run.
How do I claim federal tax credits for a financed HVAC system?
For systems placed in service during 2026, the federal 25C tax credit is no longer available as it expired on December 31, 2025. You should instead focus on local utility rebates from providers like Duke Energy or OUC. These programs offer instant or mail-in rebates for qualifying high-efficiency equipment. Our team provides the necessary AHRI certificates and technical documentation you’ll need to submit these claims successfully and reduce your total project cost.
What happens to my AC financing if I sell my Florida home?
If you have a traditional unsecured HVAC loan, it typically remains your personal responsibility or is paid off during the home sale using the proceeds. However, if you used a PACE program, the financing is attached to the property as a tax lien. Most mortgage lenders require PACE assessments to be paid in full before a title transfer can occur. It’s important to disclose your financing type to your real estate agent early in the selling process.